Lowest cost overallNo annual fee
PNB
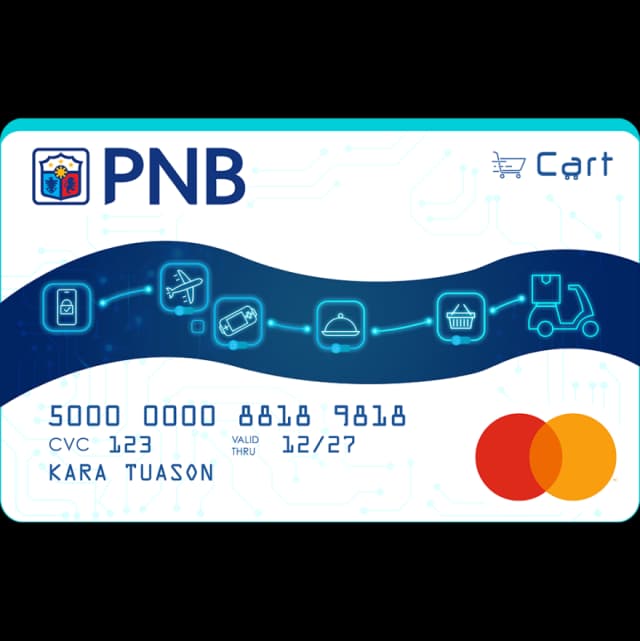
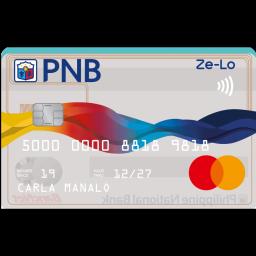
PNB Ze-Lo Mastercard
- Annual fee
- ₱0free for life
- Min. income
- ₱120,000a year
- Interest
- 2.5%a month
- Foreign fee
- 2.5%of the amount
Year-one cost₱1,008
Zero late payment fees
Updated
Credit card comparison · 2026
All 144 cards from 13 BSP-supervised banks, compared on annual fee, interest, minimum income and foreign fees from each bank's own fee table.
Bank
Ranked by lowest year-one cost · restricted cards listed last
PNB
Zero late payment fees
Maya
Miles: 1 Maya Mile per ₱40 of eligible spending, with up to 10x at Maya Black Preferred merchants; the bonus is not a rate for every purchase.
Zero annual fee. A separate ₱50 monthly inactivity fee starts after six months from approval and applies to a billing cycle with no purchases, cash advances or other transactions.
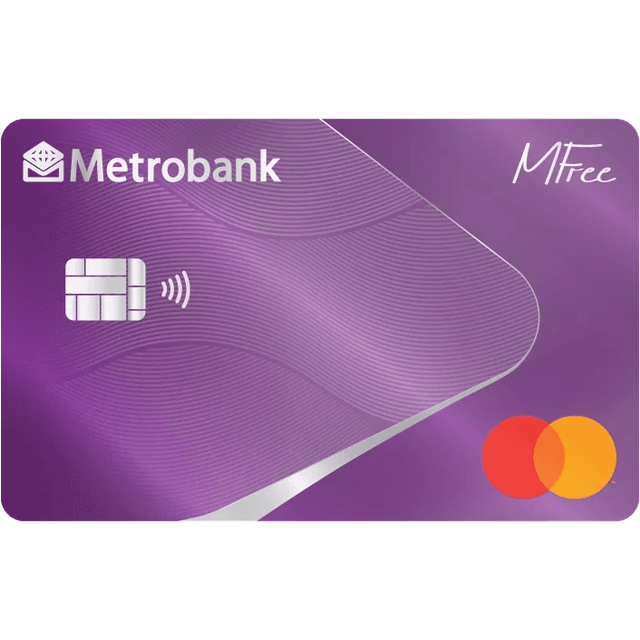
Metrobank
Zero annual fee for life.
Needs: Must be a principal cardholder with another bank for at least 9 months with a credit limit of at least PHP 50,000
Metrobank
Zero annual fee for life.
EastWest
Points: Earn one Platinum Rewards Point per ₱40 of valid spending, rounded down separately for each transaction.
China Bank
Points: Earn one point per ₱30 of qualified spending.
Needs: A principal credit card from another bank, active for at least 12 months
MariBank
Cash back: Cashback applies to eligible local in-store and local online purchases.
PNB
Get your virtual credit card fast
PNB
Points: Earn one point per ₱70 of eligible spending.
PNB
Points: Earn one point per ₱40 at The Travel Club and per ₱70 on other eligible spending.
UnionBank
Zero annual fee for life on principal and supplementary U cards, with no spending requirement.
UnionBank
Pay at least the minimum due on time to receive 10% of cash and retail interest back in the next billing cycle.
Six things decide it. Tap one to sort every card by it.
Editor's picks
One card for each common need, picked only from cards anyone can apply for. Figures come from each bank's own fee table; open Details for the source.
₱1,008 on the ₱20,000 test, the lowest of the 123 cards anyone can apply for that print both figures (the middle one costs ₱4,212). Annual fee: no annual fee; interest 2.5% a month; income from ₱120,000 a year. (PNB fee table, June 2026)
Watch out: Foreign currency purchases cost 2.5% extra.
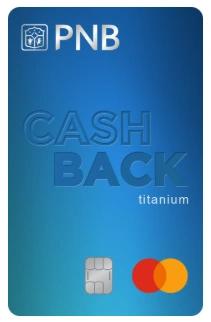
₱1,250 back a month on ₱20,000 of the quarter’s qualifying 8% merchant categories, after the cap, the most of any cash back card anyone can apply for. Annual fee: ₱2,500 a year; income from ₱120,000 a year. (PNB fee table, June 2026)
Watch out: The fee, ₱2,500 a year, is charged from year 2.
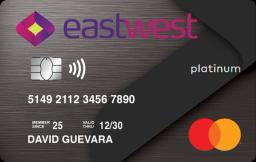
The lowest yearly fee of any card anyone can apply for that lists airport lounge access: no annual fee. Year-one cost on the ₱20,000 test: ₱1,212. (EastWest current official fee schedule)
Watch out: Needs at least ₱1,800,000 a year in income.
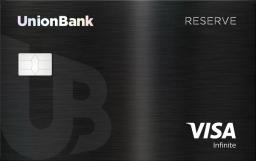
Adds 1% to purchases in foreign currency, the lowest of any card anyone can apply for (the middle card charges 2.5%). Annual fee: ₱12,000 a year. (UnionBank fee table, July 2025)
Watch out: The fee, ₱12,000 a year, has no waiver on the fee table.
The lowest year-one cost of any miles card, ₱1,212 on the ₱20,000 test. Annual fee: no annual fee; income from ₱180,000 a year. 1 Maya Mile per ₱40 spent. (Maya card page)
Watch out: The no-fee terms depend on use: Zero annual fee. A separate ₱50 monthly inactivity fee starts after six months from approval and applies to a billing cycle with no purchases, cash advances or other transactions.
A secured card uses your own bank deposit as security; document requirements vary by bank. Annual fee: not published; year-one cost on the ₱20,000 test: not published. (UnionBank card page)
Watch out: Interest is 3% a month, the legal maximum.
Free for life with no conditions; income from ₱350,000 a year. Year-one cost on the ₱20,000 test: ₱1,212. (Metrobank fee table, 15 June 2026)
Watch out: Not a first card: you need a card from another bank already.
₱0 in fees over two years, the lowest of any card anyone can apply for with a published perk. 1 Mabuhay Mile per ₱58 spent; income from ₱120,000 a year. (PNB fee table, June 2026)
Watch out: The fee, ₱1,000 a year, is charged from year 4.
Among the lowest incomes asked on the first card list, ₱120,000 a year, with no card history needed. Annual fee: ₱300 a year. (PNB fee table, June 2026)
Watch out: The fee, ₱300 a year, is charged from year 2.
Free lounge visits: unlimited, at Marhaba at NAIA T1 and Clark T2 international departures; cardholder only, one visit per 24 hours, three-hour stay; confirm current availability, the most of any card anyone can apply for. Annual fee: ₱4,000 a year. (BDO fee table, September 2026)
Watch out: The fee, ₱4,000 a year, is waived only if you spend ₱450,000 a year.
₱9.00 back per ₱1,000 spent at the bank's own points value, the most of any card anyone can apply for. Annual fee: ₱5,000 a year. (Security Bank fee table, 29 August 2025)
Watch out: Needs at least ₱3,000,000 a year in income.
| Best for | Card | Annual fee | Min. yearly income | Interest / month | Year-one cost* | Apply |
|---|---|---|---|---|---|---|
| Lowest cost overall | PNB Ze-Lo Mastercard | ₱0 free for life | ₱120,000 | 2.5% | ₱1,008 | Apply |
| Cash back | PNB Cashback Titanium Mastercard | ₱2,500 a year, 1st year free | ₱120,000 | 3% | ₱3,712 | Apply |
| Lounge access | EastWest Platinum Mastercard | ₱0 free for life | ₱1,800,000 | 3% | ₱1,212 | Apply |
| Spending abroad | UnionBank Reserve Visa Infinite | ₱12,000 a year | Not stated | 3% | ₱13,212 | Apply |
| Miles on a budget | Maya Black Credit Card | ₱0 if you use it | ₱180,000 | 3% | ₱1,212 | Apply |
| Secured card | UnionBank Rewards Secured Credit Card | Confirm ask the bank | Not stated | 3% | - | Apply |
| No annual fee, ever | PSBank Credit Mastercard | ₱0 free for life | ₱350,000 | 3% | ₱1,212 | Apply |
| All-round with perks | PNB-PAL Mabuhay Miles NOW Mastercard | ₱1,000 a year, 1st year free | ₱120,000 | 3% | ₱2,212 | Apply |
| First card | PNB Visa Classic | ₱300 a year, 1st year free | ₱120,000 | 3% | ₱1,512 | Apply |
| Most lounge visits | BDO American Express Explorer Credit Card | ₱4,000 a year, waived with spend | ₱792,000 | 3% | ₱5,212 | Apply |
| Points value | Security Bank World Mastercard | ₱5,000 a year | ₱3,000,000 | 3% | ₱6,212 | Apply |
*Interest on a ₱20,000 balance repaid in 3 equal monthly payments, plus one year of the principal card's annual fee. See how we rank.
Cards you can get on your yearly income: ₱180K₱250K₱360K₱500K₱1M
How the picks are chosen: each follows the rule printed with it, and the cost figure is one year's fee plus the interest on ₱20,000 paid off in 3 equal monthly payments. Only cards anyone can apply for are picked. Fees as printed on each bank's fee table in force: BDO (September 2026), BPI (July 2026), Metrobank (15 June 2026), Security Bank (29 August 2025), UnionBank (July 2025), Maybank (10 February 2023), PNB (June 2026), China Bank (February 2023), Maya (9 October 2026); RCBC, EastWest, HSBC and MariBank print no date on their fee tables.
Next step: open a pick's page for its full fee table, requirements and the bank's own application link, or use the income links above to see every card you qualify for.
Guide
The best card is the one you qualify for and that costs least for the way you pay. Work through these in order.
| Type | Best if you... | Watch out for |
|---|---|---|
| No annual fee | want a low-cost card you use now and then | usage rules; fewer perks |
| Cash back | spend on groceries, bills and fuel | monthly cash back caps |
| Travel and miles | fly at least twice a year | high fees, foreign fees, miles expiry |
| Rewards points | want flexible redemptions | points expiry and conversion rates |
| First card | are applying for your first card | low limits |
| Secured cards | have no card history yet | your deposit stays on hold |
| Store cards | shop often at one store or app | rebates only at that store |
| Business cards | run a company or sole proprietorship | company documents and liability |
Getting approved
17 cards open to the public ask for ₱180,000 a year or less; the lowest is ₱120,000.
Each bank page lists that bank's exact documents.
No card history? A secured card uses your own bank deposit as security, such as the BDO Secured Credit Card or UnionBank Rewards Secured Credit Card.
| Bank | Card hotline |
|---|---|
| BDO | (+632) 8888-0000 or 1-800-10-88880000 all BDO contact numbers |
| BPI | (+632) 889-10000 or 1-800-188-89-100 all BPI contact numbers |
| Metrobank | (02) 88-700-700 or 1-800-1888-5775 all Metrobank contact numbers |
| Security Bank | (02) 8887-9188 or 1-800-1-888-1250 all Security Bank contact numbers |
| RCBC | (02) 8888-1888 or 1-800-10-888-1888 all RCBC contact numbers |
| UnionBank | (+632) 8841-8600 or 1-800-1888-2277 all UnionBank contact numbers |
| EastWest | (632) 8888-1700 or 1-800-1888-8600 all EastWest contact numbers |
| HSBC | (02) 8858-0000 or (02) 7976-8000 or +1-800-1-888-8555 all HSBC contact numbers |
| Maybank | (02) 8588-3888 or 1-800-10-588-3888 all Maybank contact numbers |
| PNB | (+632) 8818 9818 or 1800-10-818-9-818 all PNB contact numbers |
| China Bank | +632 888-55-888 or 1-800-1888-5888 all China Bank contact numbers |
| Maya | +632 8845 7788 or 1-800-1084-57788 all Maya contact numbers |
The rules
BSP Circular No. 1165, s.2023 caps interest and finance charges on all credit card transactions at 36% a year. The Monetary Board approved it in Resolution No. 55 on 13 January 2023. It applies to banks and to non-bank card issuers alike. Change coming, not yet in force: BSP Circular No. 1242, s.2026, signed 10 November 2026, takes effect 15 calendar days after its publication (the BSP's list of published issuances shows 13 November 2026, which would make it 28 November 2026). It raises the instalment add-on cap from 1% to 1.5% a month and the cash advance fee cap from ₱200 to ₱300, keeps the 3% a month (36% a year) interest cap, and makes the caps subject to periodic review; in its media release the BSP says the new ceilings apply only to new transactions from the effectivity date, and card instalment loans taken before then keep their agreed terms. Until then BSP Circular No. 1165, s.2023 applies, under which the BSP reviews the caps every six months. The change is explained in the credit card interest rate cap.
139 of the 141 cards with a published rate charge the full 3%. The ones that charge less: BPI Free+ Card (2.5%, depositors only), PNB Ze-Lo Mastercard (2.5%).
"Banks shall impose an interest or finance charge on all credit card transactions not to exceed an annual interest rate of thirty-six (36%) except credit card installment loans which shall be subject to monthly add-on rate not exceeding one (1) percent: Provided, That in the case of credit card cash advances, aside from the foregoing applicable maximum interest rate caps, no other charge or fee shall be imposed or collected apart from the processing fee in the maximum amount of Php200.00 per transaction."
BSP Circular No. 1165, s.2023
Source: BSP Circular No. 1165, s.2023 · BSP Circular No. 1242, s.2026 (not yet in force) · BSP media release on Circular No. 1242, November 2026
Card issuers
13 banks, each on the BSP Verifier list of supervised institutions dated Sep 28, 2026. Open a bank for its full card list, fees, requirements, promos and hotline. The fee table date is the one each bank prints on its own table.
| Bank | Cards | Annual fee range | Lowest-cost card | Fee table dated | BSP list | Bank page |
|---|---|---|---|---|---|---|
| BDO | 22 | ₱1,200 to ₱5,500 | BDO HOPE Mastercard | September 2026 | Universal and commercial bank, ID 30 | View BDO cards → |
| BPI | 9 | ₱0 to ₱5,500 | BPI Edge Card | July 2026 | Universal and commercial bank, ID 29 | View BPI cards → |
| Metrobank | 11 | ₱0 to ₱6,000 | PSBank Credit Mastercard | 15 June 2026 | Universal and commercial bank, ID 33 | View Metrobank cards → |
| Security Bank | 5 | ₱0 to ₱5,000 | Security Bank Platinum Mastercard | 29 August 2025 | Universal and commercial bank, ID 2 | View Security Bank cards → |
| RCBC | 18 | ₱0 to ₱6,000 | RCBC Landmark Anson's Mastercard | No date printed | Universal and commercial bank, ID 1 | View RCBC cards → |
| UnionBank | 26 | ₱0 to ₱12,000 | UnionBank U Platinum Mastercard | July 2025 | Universal and commercial bank, ID 3 | View UnionBank cards → |
| EastWest | 12 | ₱0 to ₱5,000 | EastWest Platinum Mastercard | No date printed | Universal and commercial bank, ID 32 | View EastWest cards → |
| HSBC | 5 | ₱2,500 to ₱12,500 | HSBC Red Platinum Mastercard | No date printed | Universal and commercial bank, ID 12 | View HSBC cards → |
| Maybank | 5 | ₱0 to ₱3,500 | Maybank Visa Classic | 10 February 2023 | Universal and commercial bank, ID 19 | View Maybank cards → |
| PNB | 15 | ₱0 to ₱6,000 | PNB Ze-Lo Mastercard | June 2026 | Universal and commercial bank, ID 34 | View PNB cards → |
| China Bank | 12 | ₱0 to ₱6,000 | China Bank Freedom Mastercard | February 2023 | Universal and commercial bank, ID 31 | View China Bank cards → |
| Maya | 3 | ₱0 | Maya Black Credit Card | 9 October 2026 | Digital bank, ID 462 | View Maya cards → |
| MariBank | 1 | ₱0 | MariCard Credit | No date printed | Digital bank, ID 211 |
Methodology
Rewards and perks are worth different amounts to different people. Cost is the same for everyone, so the default ranking puts every card through one test.
Scope: the picks count only cards anyone can apply for. Cards limited to depositors, club members or invited clients are on the board, marked, but never picked or ranked.
monthly payment = r × 20,000 ÷ (1 − (1 + r)^−3)
interest = 3 × payment − 20,000
year-one cost = interest + annual fee
r is the card's monthly interest rate. At the 3% cap the interest is ₱1,212; at 2.5% it is ₱1,008. First-year fee waivers are ignored, because the fee applies from year two.
BSP Circular No. 1165, s.2023; BSP Verifier, list dated Sep 28, 2026.
Card fees and interest do not lower the tax on a salary: Section 34 of the Tax Code allows no deductions against compensation income. A self-employed cardholder who takes the 40% optional standard deduction gets it in place of itemized expenses, so card charges do not reduce tax there either.
Check your take-home pay with the salary tax calculator.
FAQ
It depends on how you pay and what you spend on. On cost, the PNB Ze-Lo Mastercard (PNB): ₱1,008 on a ₱20,000 balance paid off in 3 months plus a year of fees, the lowest of the 123 cards anyone can apply for that print both figures. With perks, the PNB-PAL Mabuhay Miles NOW Mastercard (PNB) has the lowest fees over two years among cards with a published perk. If you pay in full every month, pick a card with no annual fee whose rewards match your spending (12 cards open to the public have none). If you travel, see the travel cards; for groceries and bills, the cash back cards.
For a first card, look at the income rule first. The PNB Ze-Lo Mastercard asks for the least, ₱120,000 a year; annual fee: no annual fee. 17 cards open to the public ask for ₱180,000 a year or less. See all first credit cards.
Going by the income each bank asks, the PNB Ze-Lo Mastercard (PNB) asks the least: ₱120,000 a year. 17 cards open to the public ask for ₱180,000 a year or less. A secured card, such as the BDO Secured Credit Card or UnionBank Rewards Secured Credit Card, uses your bank deposit as security; document requirements vary by bank. Approval also depends on your documents and credit record.
12 cards open to the public have no annual fee, with no conditions or only a monthly-use condition. The no annual fee list separates the cards free for life from those free only with a condition.
It depends on what you value. For airport lounges at the lowest fee, the EastWest Platinum Mastercard (no annual fee). For spending abroad, the UnionBank Reserve Visa Infinite has the lowest foreign transaction fee of any card anyone can apply for, at 1%. For miles at the lowest cost, the Maya Black Credit Card. Compare all travel credit cards.
A valid government ID and proof of income: payslips or a certificate of employment if employed, or an income tax return if self-employed. You must meet the card's minimum yearly income, and 25 cards here also ask for a card you already hold from another bank.
Pick a card whose income rule you meet, then apply on the bank's website or app, or at a branch, with a government ID and proof of income (payslips or a certificate of employment if employed; an income tax return if self-employed). Each bank page here has that bank's own steps, documents, application status tracker and hotline.
36% a year, which is 3% a month, under BSP Circular No. 1165, s.2023. Instalment plans are capped at a 1% monthly add-on rate, and a cash advance can carry a processing fee of at most ₱200, with no other fee. 139 of the 141 cards with a published rate charge the full cap. Change coming, not yet in force: BSP Circular No. 1242, s.2026, signed 10 November 2026, takes effect 15 calendar days after its publication (the BSP's list of published issuances shows 13 November 2026, which would make it 28 November 2026). It raises the instalment add-on cap from 1% to 1.5% a month and the cash advance fee cap from ₱200 to ₱300, keeps the 3% a month (36% a year) interest cap, and makes the caps subject to periodic review; in its media release the BSP says the new ceilings apply only to new transactions from the effectivity date, and card instalment loans taken before then keep their agreed terms. Until then BSP Circular No. 1165, s.2023 applies, under which the BSP reviews the caps every six months. See the credit card interest rate cap, or use the interest calculator to see what a balance costs.
Banks set the limit when they approve you, based on your income and credit record, and none of the banks here prints a limit-by-salary table. What a salary decides up front is which cards you can apply for: ₱20,000 a month is ₱240,000 a year, so look for cards with a stated minimum at or below that.
There is no set number. One card you pay in full every month builds a credit record at the lowest cost. A second card can make sense for a different network (for example JCB for Japan) or a reward you use, but every extra card can add an annual fee and another due date to track.
BDO offers 22 cards with yearly fees of ₱1,200 to ₱5,500; BPI offers 9 with fees of ₱0 to ₱5,500. On a ₱20,000 balance over 3 months plus a year of fees, the cheapest BDO card is the BDO HOPE Mastercard and the cheapest BPI card the BPI Edge Card; with perks, the lowest fees over two years are on the BDO ShopMore Mastercard at BDO and the not ranked at BPI. Pick the bank where you already bank, then the card whose income rule and rewards fit.
A debit card spends money already in your bank account. A credit card spends the bank's money up to a limit, which you repay by the due date; whatever you leave unpaid is charged interest of up to 3% a month, and most credit cards carry an annual fee.
Promos change every few weeks, so each bank page here links to that bank's own promos page instead of listing them.
Best-for lists: No annual fee · Travel · Cash back · First card · Secured cards · Rewards points · Store cards · Business cards · Interest calculator
TaxCalculator.com.ph compares cards; we do not issue cards, approve applications or set rates. Fees and terms change, so confirm them on the bank's site before you apply. Figures last checked Oct 16, 2026.