Check the total repayment, processing fee and payment timing before moving a balance. Keep paying your original card until the receiving bank confirms settlement.
What will your balance transfer cost?
Enter the offer your bank gave you. This illustration assumes the processing fee is paid separately and payments are made on time.
The starting example uses a ₱20,000 balance, 0.55% monthly add-on for 12 months and a ₱350 fee. Replace these figures with your bank’s approved offer.
Total including fee: ₱21,670.00
Balance transferred
₱20,000.00
Total add-on interest
₱1,320.00
Processing fee
₱350.00
Monthly payment before the final month
₱1,776.66
Final payment, including rounding difference
₱1,776.74
What changes with a longer term?
These examples use the balance, rate and fee you entered. Your bank may offer different rates for different terms; confirm each quote before choosing.
Same balance and add-on rate across four repayment terms
Months
Monthly payment*
Interest
Total with fee
12
₱1,776.66
₱1,320.00
₱21,670.00
18
₱1,221.11
₱1,980.00
₱22,330.00
24
₱943.33
₱2,640.00
₱22,990.00
36
₱665.55
₱3,960.00
₱24,310.00
*The final payment includes any rounding difference. The processing fee is paid separately in this illustration.
The bank’s actual schedule and fee timing can differ. This is an add-on cost illustration, not an effective annual interest rate. It excludes late charges, residual charges on the original card and new purchases.
Compare the offer you actually qualify for
Metrobank’s 2026 offer
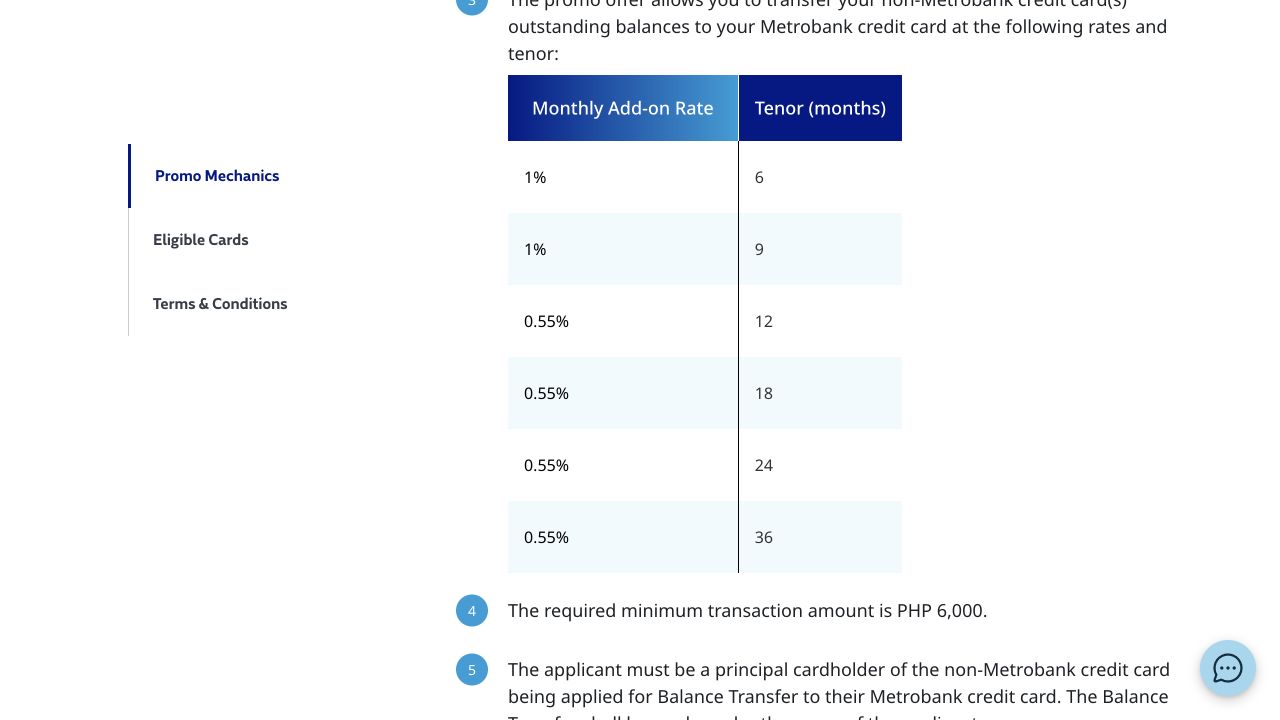
The published offer runs January 1–December 31, 2026 for listed eligible principal cardholders in good standing. It lists 0.55% monthly add-on for 12, 18, 24 or 36 months, and 1% for six or nine months.
The minimum transfer is ₱6,000, with a ₱350 processing fee. You must be the principal holder of the original card. The transferred amount plus total interest must fit within your available credit limit when you apply. Metrobank still assesses the application, and an approved transfer cannot be cancelled.
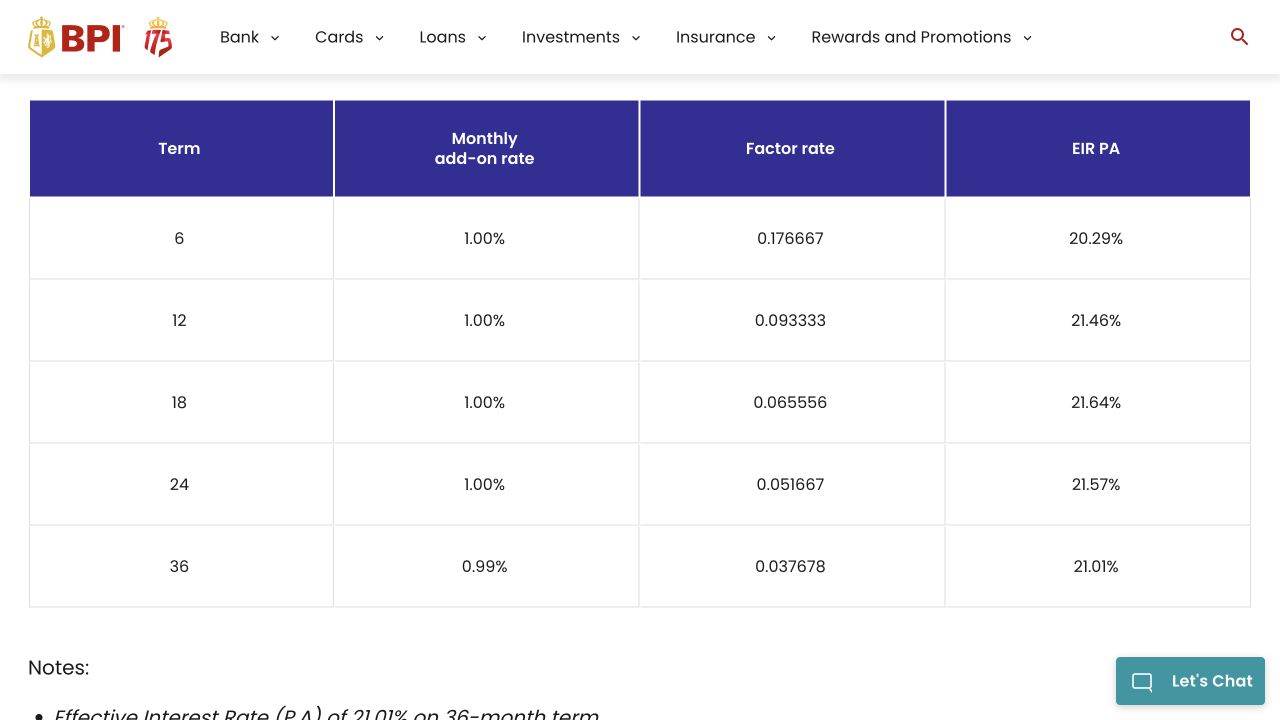
The bank’s table lists 1% monthly add-on for six to 24 months, or 0.99% for 36 months. Its ₱20,000, 12-month example shows ₱2,400 total interest before the service fee.
The service fee is ₱500 for transfers up to ₱50,000, or ₱700 above ₱50,000, effective September 17, 2026. For the ₱20,000 example, principal plus interest and the ₱500 fee totals ₱22,900, excluding other charges. Confirm your own offer before applying.
BPI Omni and Free+ cards do not currently support instalments. BPI’s general S.I.P. terms also exclude Corporate and eCredit cards. Check eligibility for your exact card before submitting an application.
For early repayment, BPI lists ₱550 plus 2% of the original loan amount before the first billing. After the first billing, it lists ₱550 plus the next month’s applicable interest calculated on the declining balance. Ask BPI for the full settlement amount.
Before applying, ask BPI where the money will go and who must pay your old card. Its product page says proceeds are credited to a BPI account, while its transfer terms describe payment directly to the original issuer through bills payment or Bancnet. Confirm the arrangement for your application. Keep making required payments on the old card until settlement is confirmed, and check for any remaining charges. BPI transfer and repayment terms.
BPI’s rate table, captured October 12, 2026. For 12 months, the bank lists 1% monthly add-on and 21.46% EIR PA. The service fee is charged separately. View full-size screenshot.
Security Bank’s personalised offers
Ask for the rate assigned to your account before comparing costs. The bank publishes several pricing options; the lowest rate shown is not an offer for every cardholder.
Its application terms require a principal cardholder in good standing with both banks, an original card in the same name and a minimum transfer of ₱5,000. Approval can be for less than the amount requested. The approved amount cannot exceed your available Security Bank credit limit or the total due on the original card.
An approved transfer cannot be reversed. Security Bank’s published terms allow a ₱500 processing fee if you end the transfer before the agreed term. Continue paying the original card until settlement; delays can still leave you owing interest or late charges there. The monthly instalment becomes part of your statement balance. Leaving any of that balance unpaid can trigger regular finance charges and, where applicable, late-payment charges.
For BDO and UnionBank balances, prepare the latest complete statement with every page visible and no password protection. For BPI, have the customer number from your statement ready. If you already have Security Bank Ready Cash or a balance transfer, its help page says you must have repaid at least half of that balance.
Security Bank describes five banking days for processing, followed by another two to three banking days for an approved transfer. Confirm the processing fee and keep paying the original card until settlement. Get an early-settlement quote before paying off the instalments. Security Bank document requirements and payment timing.
Sources checked October 13, 2026. Confirm the rate and conditions in your own bank offer before applying.
Applying is not the same as paying off your old card
Get a written cost quote
Confirm the amount, rate, term, fee, monthly payment and early-settlement charges.
Apply and keep paying
Continue required payments to the original issuer while the bank reviews the application.
Confirm payment arrived
Check the original account after settlement. Look for residual charges and avoid assuming the balance is zero.
Pay the new instalments
Check the receiving card’s statement and due date. Pay the full instalment shown on your statement. Metrobank says paying only the minimum or less than the total due can leave part of the instalment unpaid; the unpaid portion can then attract the card’s regular finance charges.
Metrobank’s terms distinguish processing from remittance: they describe payment within 15 business days of application and remittance within six business days after the transfer amount posts. Confirm the actual status with the bank if your original due date is approaching.
Balance-transfer questions
What is a credit card balance transfer?
You use an approved repayment arrangement on another card to pay an eligible existing card balance. Confirm whether the receiving bank pays the old issuer or credits the money to an account for you to pay it. Approval does not mean the old balance has been settled, and your old account does not automatically close.
Does a 0.55% monthly add-on rate mean 6.6% annual interest?
No. Add-on interest is calculated on the original transferred amount, while you repay that amount over time. An effective interest rate accounts for the repayment cash flows. Multiplying the monthly add-on rate by twelve does not give the effective annual rate.
Will the bank pay my old card directly?
Confirm this before applying. BPI’s product page says proceeds go to a BPI account, while its general transfer terms describe payment to the old issuer. Ask which arrangement applies to your application, who must make the payment and when it will arrive. Check the old account after settlement rather than assuming approval clears the debt.
Should I stop paying my old credit card after applying?
No. Keep making the required payments until you confirm that the transfer has settled. Charges can continue while the application is processed, and residual interest or new purchases can leave a balance on the old card.
Can I transfer a balance from someone else’s card?
Metrobank’s published 2026 offer requires you to be the principal holder of the original non-Metrobank card. Confirm ownership requirements with the receiving bank rather than assuming another person’s debt is eligible.
Can I pay the transfer off early?
Ask for an early-settlement quotation before paying extra. Metrobank’s 2026 terms list a pretermination fee of ₱550 or 5% of remaining principal, whichever is higher, plus any applicable outstanding amounts. Other banks have different conditions.
Will the transfer earn rewards?
Metrobank’s 2026 balance-transfer offer does not earn rewards points. Check the exact programme instead of assuming a transfer earns the same rewards as shopping.
Can I pay only the minimum after a balance transfer?
Pay the full amount required by your repayment arrangement and statement. Metrobank’s 2026 terms warn that a payment below the total amount due can leave part of the instalment unpaid, which can attract regular finance charges. A low transfer rate does not protect you from those charges if you underpay.
Is the lowest monthly payment always the cheapest option?
No. A longer term can lower the monthly payment while increasing total add-on interest. Compare the total including fees and choose a payment you can maintain without taking on new debt.